Posted on 22 December 2024
Trial Balance Template Excel & Google Sheets
- Free trial balance template in Excel, Google Sheets, Word and PDF, with a filled example you can copy and blank formats you can print
- Post journal entries or paste balances from any accounting software, and the trial balance, adjusted trial balance and financial statements build themselves by formula
- An Error Finder that tells you why it does not balance: transposed digits, wrong-side postings, unbalanced entries, unknown codes and opening balance errors
The 10-column extended trial balance, a post-closing trial balance, a comparative trial balance and the Indian Particulars and L.F. format, all in one file
A trial balance template is a ready-made worksheet that lists every general ledger account with its closing debit or credit balance at a set date, totals both columns to prove that debits equal credits under double-entry bookkeeping, and gives you the checked figures you need to prepare the income statement and balance sheet.


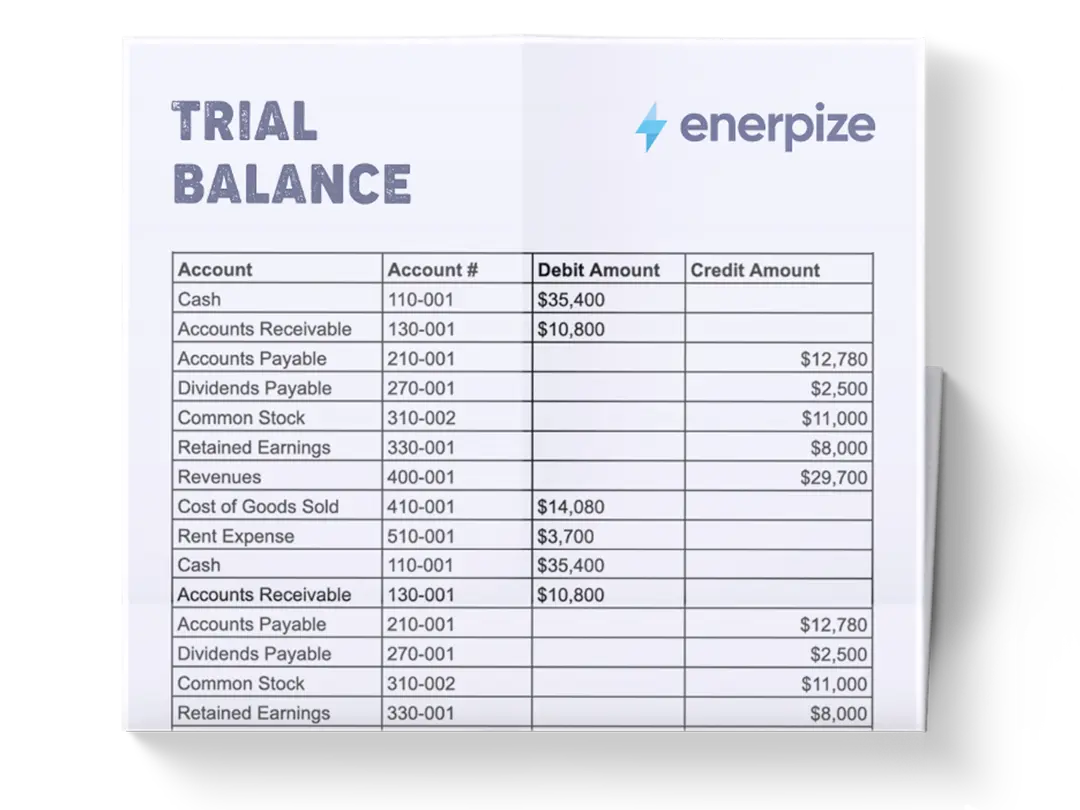
What is the Trial Balance Template?
The trial balance template is the worksheet you prepare at the end of a month, a quarter or a year to test your books before you trust them. Every account in the general ledger goes on one line. Its closing balance goes in the debit column or the credit column. Then both columns are added up. If the totals match, every entry was recorded with equal debits and credits. If they do not, something is wrong, and you want to know before the numbers reach a tax return or a bank.
The idea is older than any software. Luca Pacioli set out double-entry bookkeeping in 1494, and the closing check he described, listing every balance and proving the two sides agree, is still the trial balance we use today.
You will hear it called a trial balance sheet, a trial balance worksheet, a TB, a list of balances or, in some countries, a statement of balances. The name changes. The test does not.
Here is what a trial balance is not. It is not a balance sheet: a trial balance lists every account, including revenue and expenses, and stays inside the accounting team, while a balance sheet shows only assets, liabilities and equity and goes to owners, lenders and tax authorities. It is not the general ledger either; the ledger holds every transaction, and the trial balance holds one closing figure per account. Enerpize's guide to the difference between the general ledger and trial balance goes deeper on that one.
What Does the Trial Balance Template Contain?
Most free trial balance templates give you an account column, a debit column and a credit column. That is enough to add up. It is not enough to find out why the totals disagree, or to turn the result into financial statements. Here is every field our trial balance template uses, and why.
| Field | Why It Matters |
|---|---|
| Business name and "as at" date | A trial balance is a snapshot. Without the date, nobody knows which period the figures prove. |
| Unadjusted, adjusted or post-closing | Three different reports share the same layout. The label stops someone preparing statements from the wrong one. |
| Account code (or L.F.) | Links each line back to the chart of accounts and the ledger page it came from. |
| Account name (or Particulars) | The account as it appears in your chart of accounts, in the same order. |
| Account type | Asset, liability, equity, revenue or expense. It decides the normal side and which statement the account feeds. |
| Normal side | Debit for assets and expenses, credit for liabilities, equity and revenue, reversed for contra accounts. It is how the template spots a balance sitting on the wrong side. |
| Opening balance | Last period's closing figure. A wrong opening balance throws off every report after it. |
| Debit and credit | The closing balance of each account, in one column only. Never both. |
| Totals and difference | The test itself. The difference must be zero. |
| Statement line | Which line of the income statement or balance sheet the account rolls into. |
| Prepared by and reviewed by | Two names. The person who checks it should not be the person who posted the entries. |
If you add one field to the sheet you use today, make it the normal side. A trial balance can balance with a credit balance on cash or a debit balance on a supplier account, and both usually mean a posting went to the wrong place. The totals will not tell you. The normal side will.
What Our Trial Balance Template Includes
Before building this one, I went through the trial balance templates, worksheets and guides that rank for these searches. The free templates were static grids: type in a balance, get a total. The guides explained the divide-by-9 trick and the adjusted trial balance in words, then left you to build it yourself. The one template that automated the calculations was paid. So I built a free trial balance template that does the whole close, by formula, in one file.
From journal to trial balance, automatically. Post each journal entry line by line: date, reference, account code, description, debit or credit. Every account's period total pulls into the chart of accounts, adds to its opening balance and lands in the right column of the trial balance. Already keep your books in other accounting software? Paste its closing balances into the Import TB sheet, as separate debit and credit columns or a single signed balance, and the rest of the workbook runs on those instead.
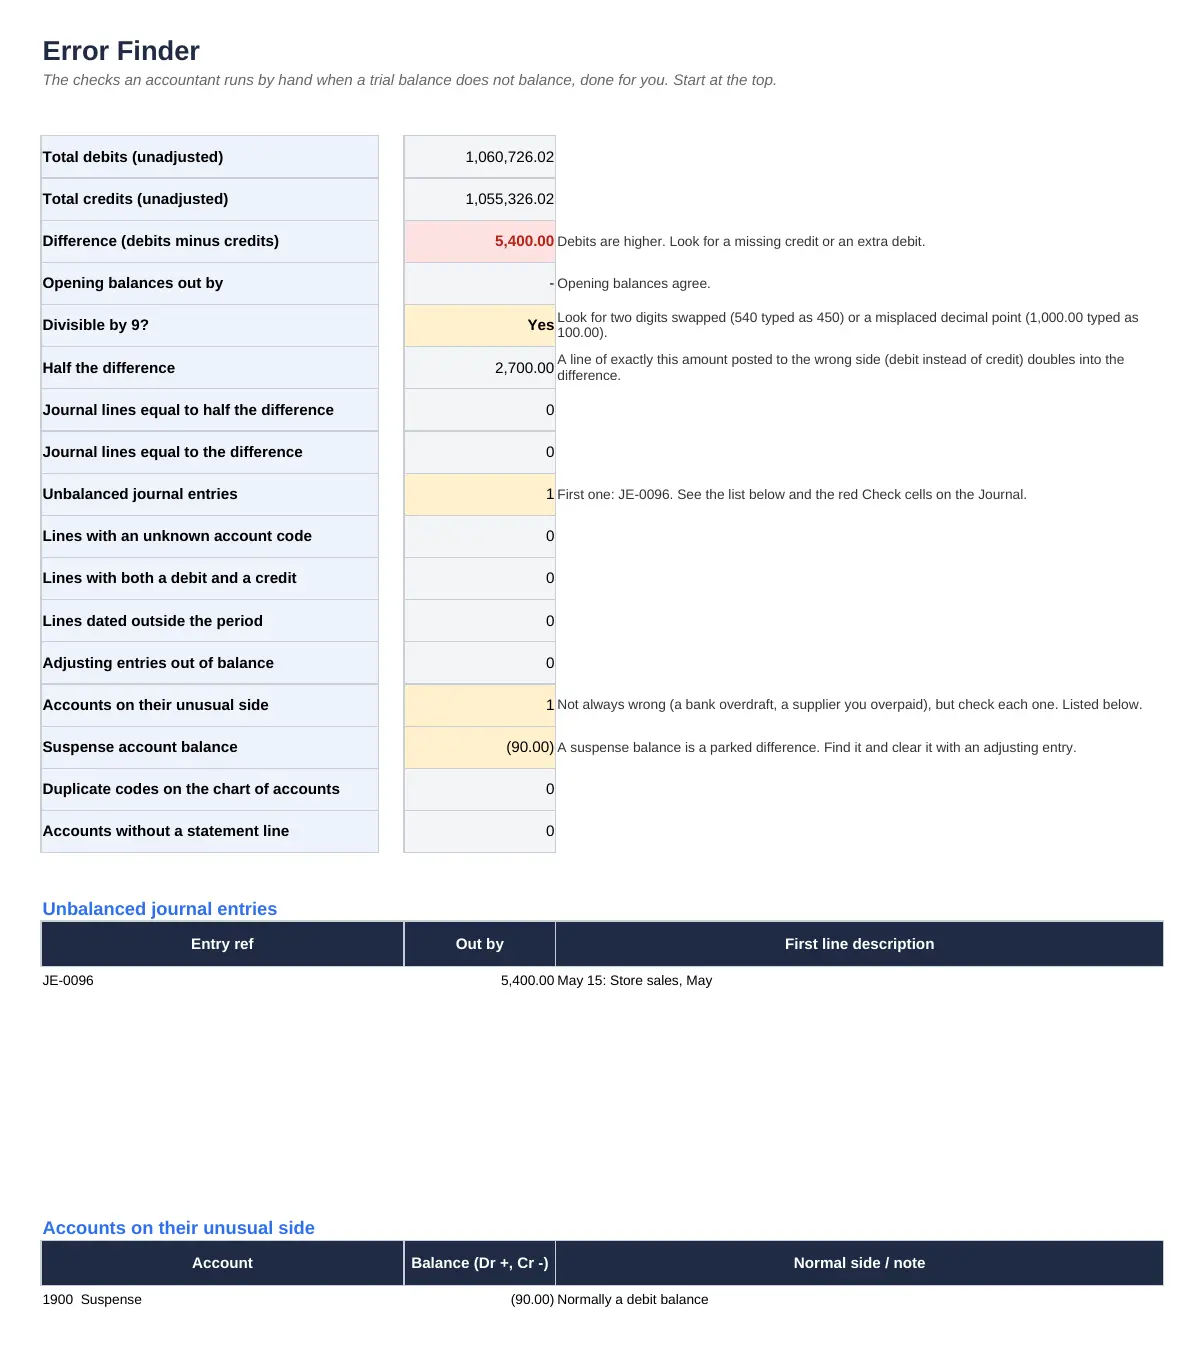
An Error Finder that does the detective work. When the totals disagree, the Error Finder sheet runs the checks an accountant runs by hand. It tests whether the difference divides by 9 (transposed digits), halves it and searches for a line of that amount (a posting on the wrong side), lists every journal entry whose debits do not equal its credits, and flags unknown codes, lines with both a debit and a credit, dates outside the period, opening balance errors and a suspense balance. In the screenshot below, one sales credit was typed with two digits swapped. The books are out by 5,400, the sheet says the difference divides by 9, and it names the exact entry.
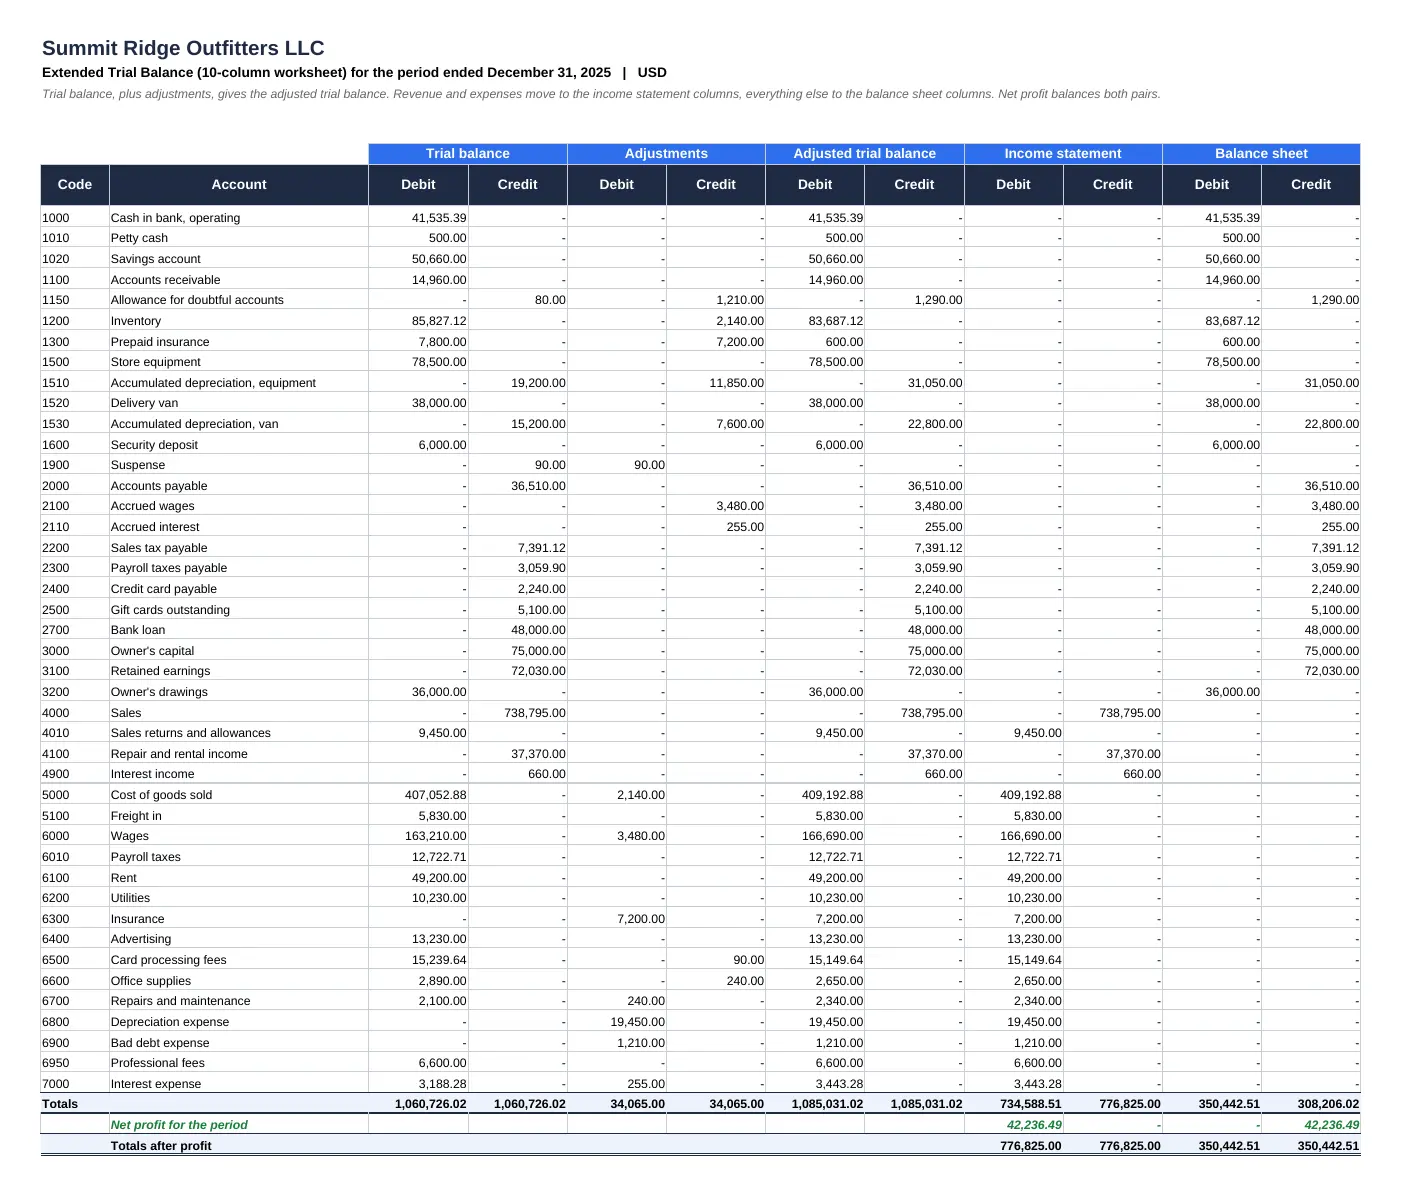
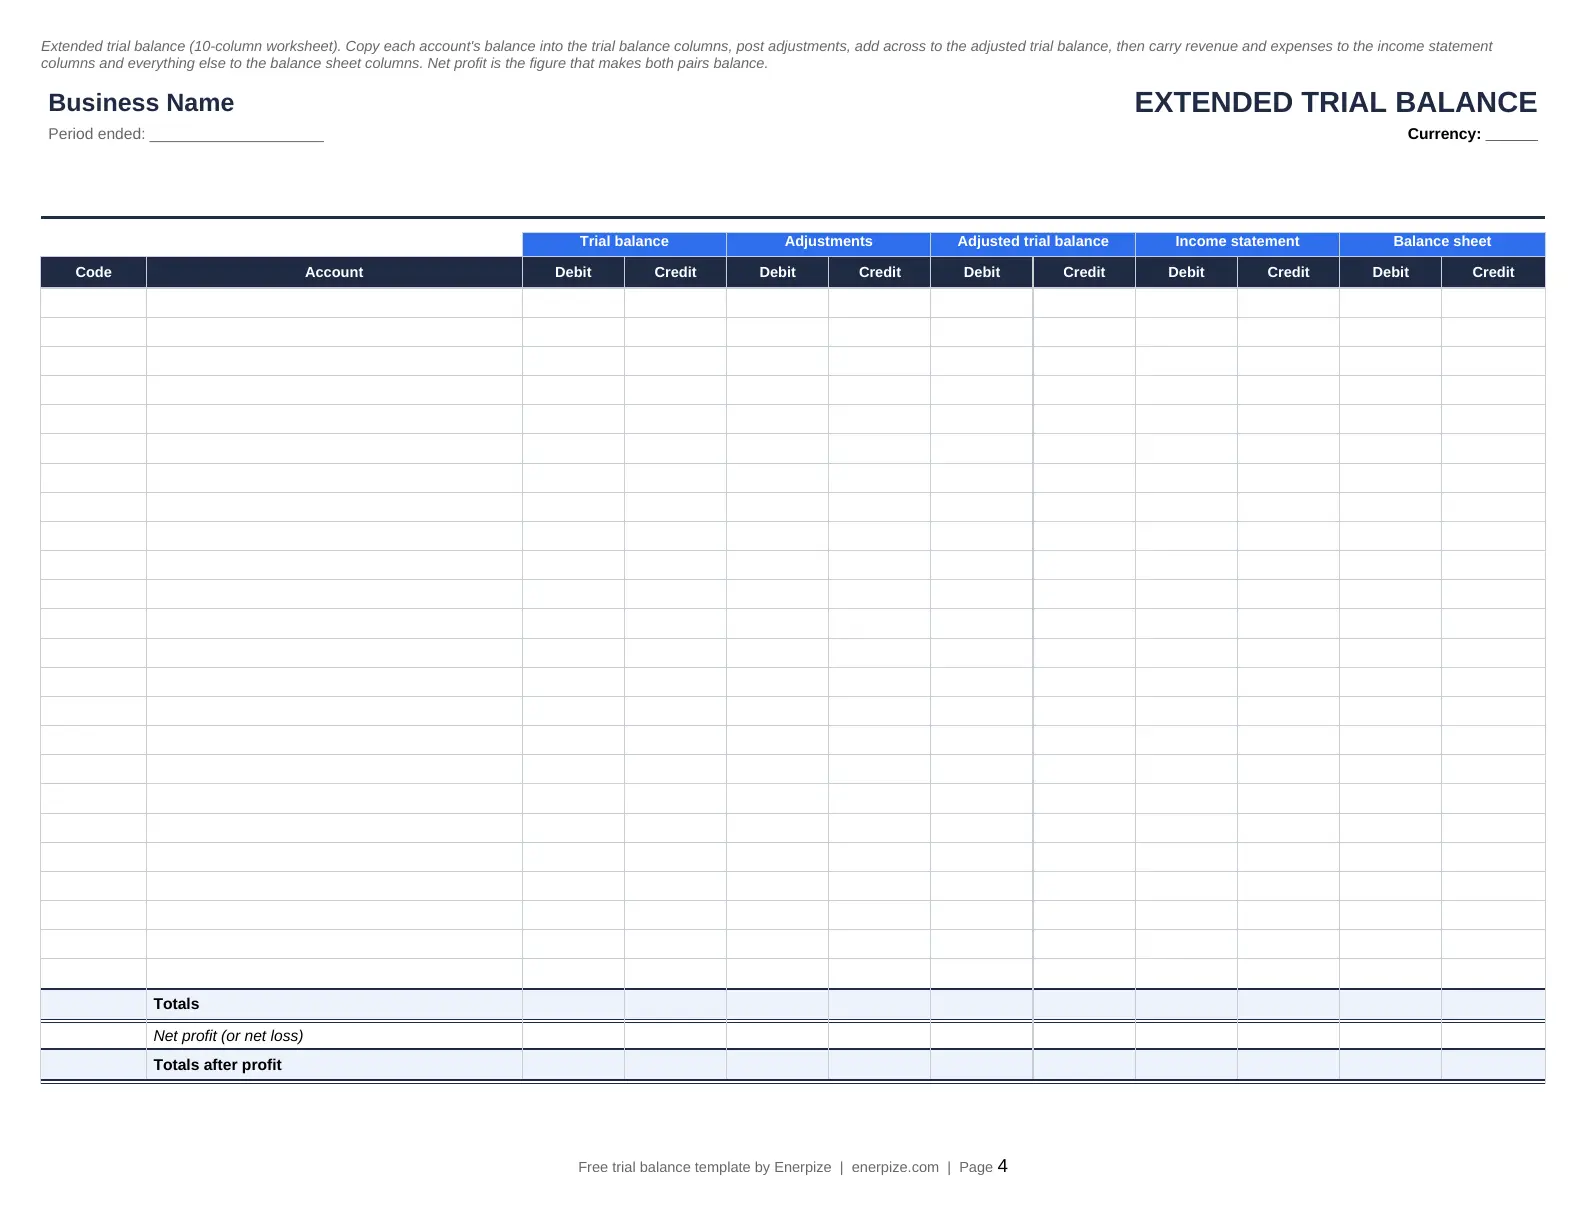
The 10-column extended trial balance. Trial balance, adjustments, adjusted trial balance, income statement and balance sheet, side by side, the way accountants and ACCA students prepare it. Revenue and expenses move to the income statement columns, everything else to the balance sheet columns, and the net profit line makes both pairs balance. Adjusting entries go on their own sheet with a type (accrual, prepayment, depreciation, inventory, bad debt, correction, suspense), so they never mix with your day-to-day journal.
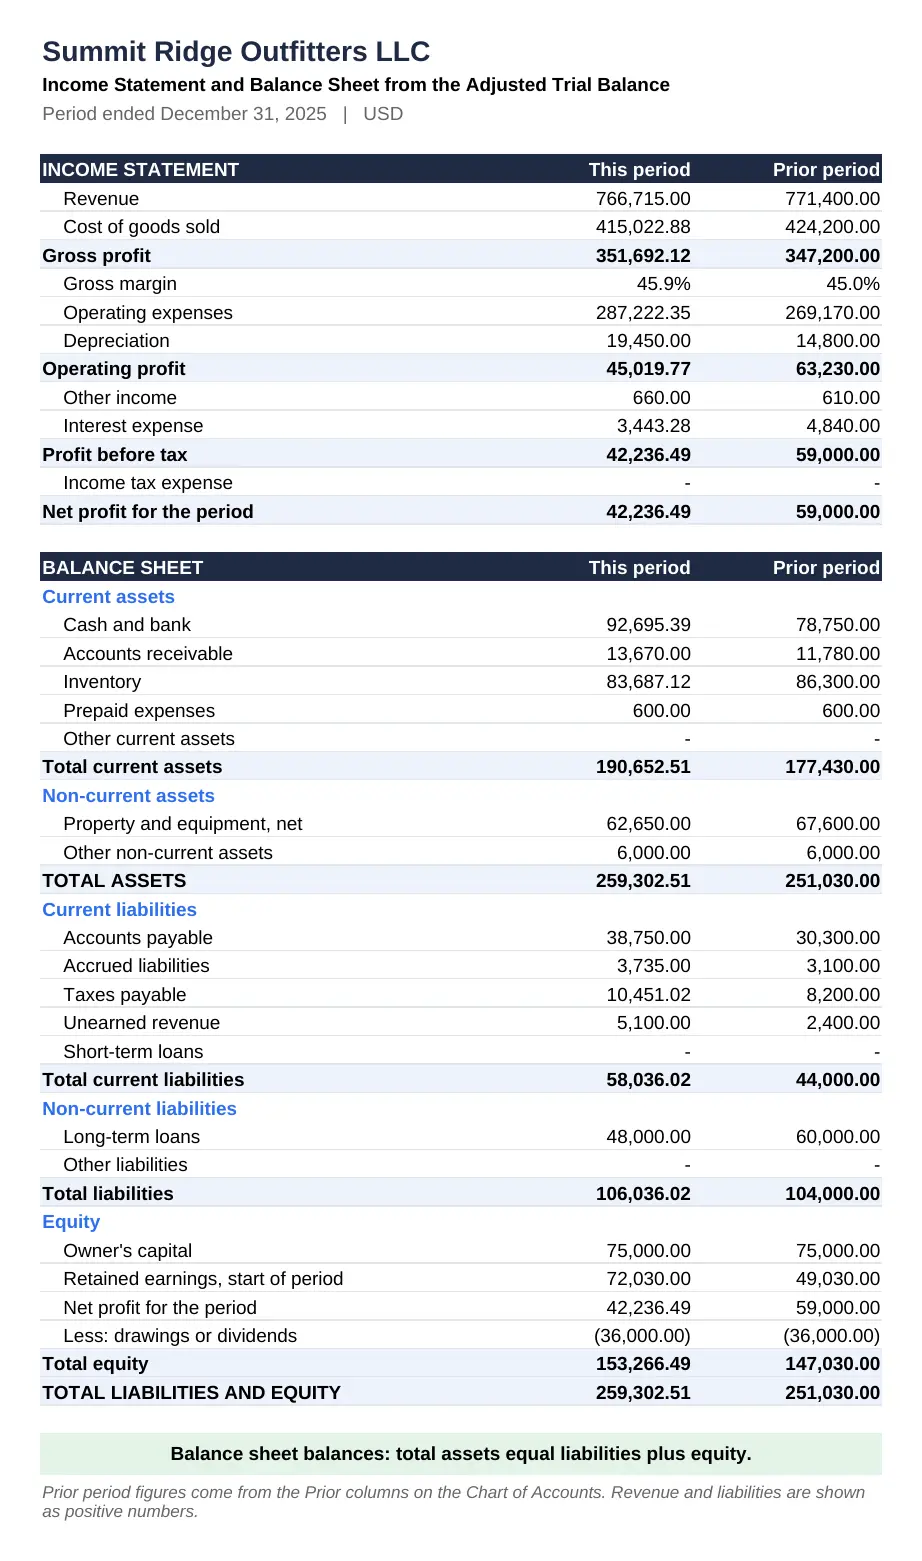
Financial statements that build themselves. Each account carries a statement line, so the adjusted trial balance rolls straight into an income statement and a balance sheet, with this period next to the prior period. The sheet tells you in plain words whether total assets equal liabilities plus equity.
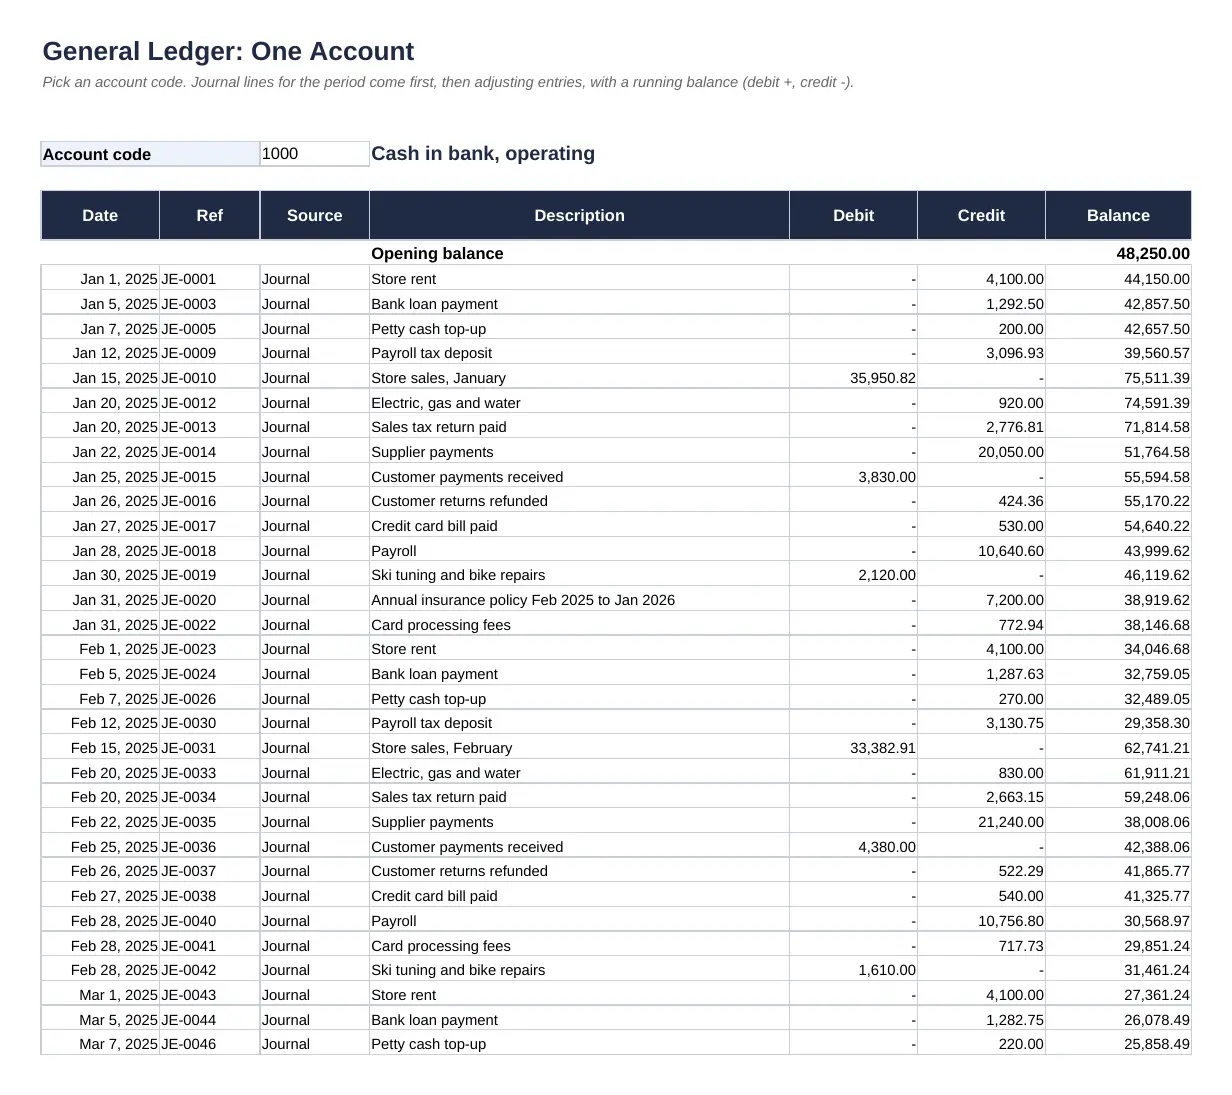
A ledger for any account. Pick an account code and see every journal line and adjusting entry for the period, with a running balance from the opening figure. That is the fastest way to trace a strange number back to the entry that caused it.
A post-closing and a comparative trial balance. The post-closing trial balance closes revenue, expenses and drawings into retained earnings for you, giving the balances that open next period. The comparative trial balance puts this period next to the last one and flags any account that moved by more than the percentage and amount you set.
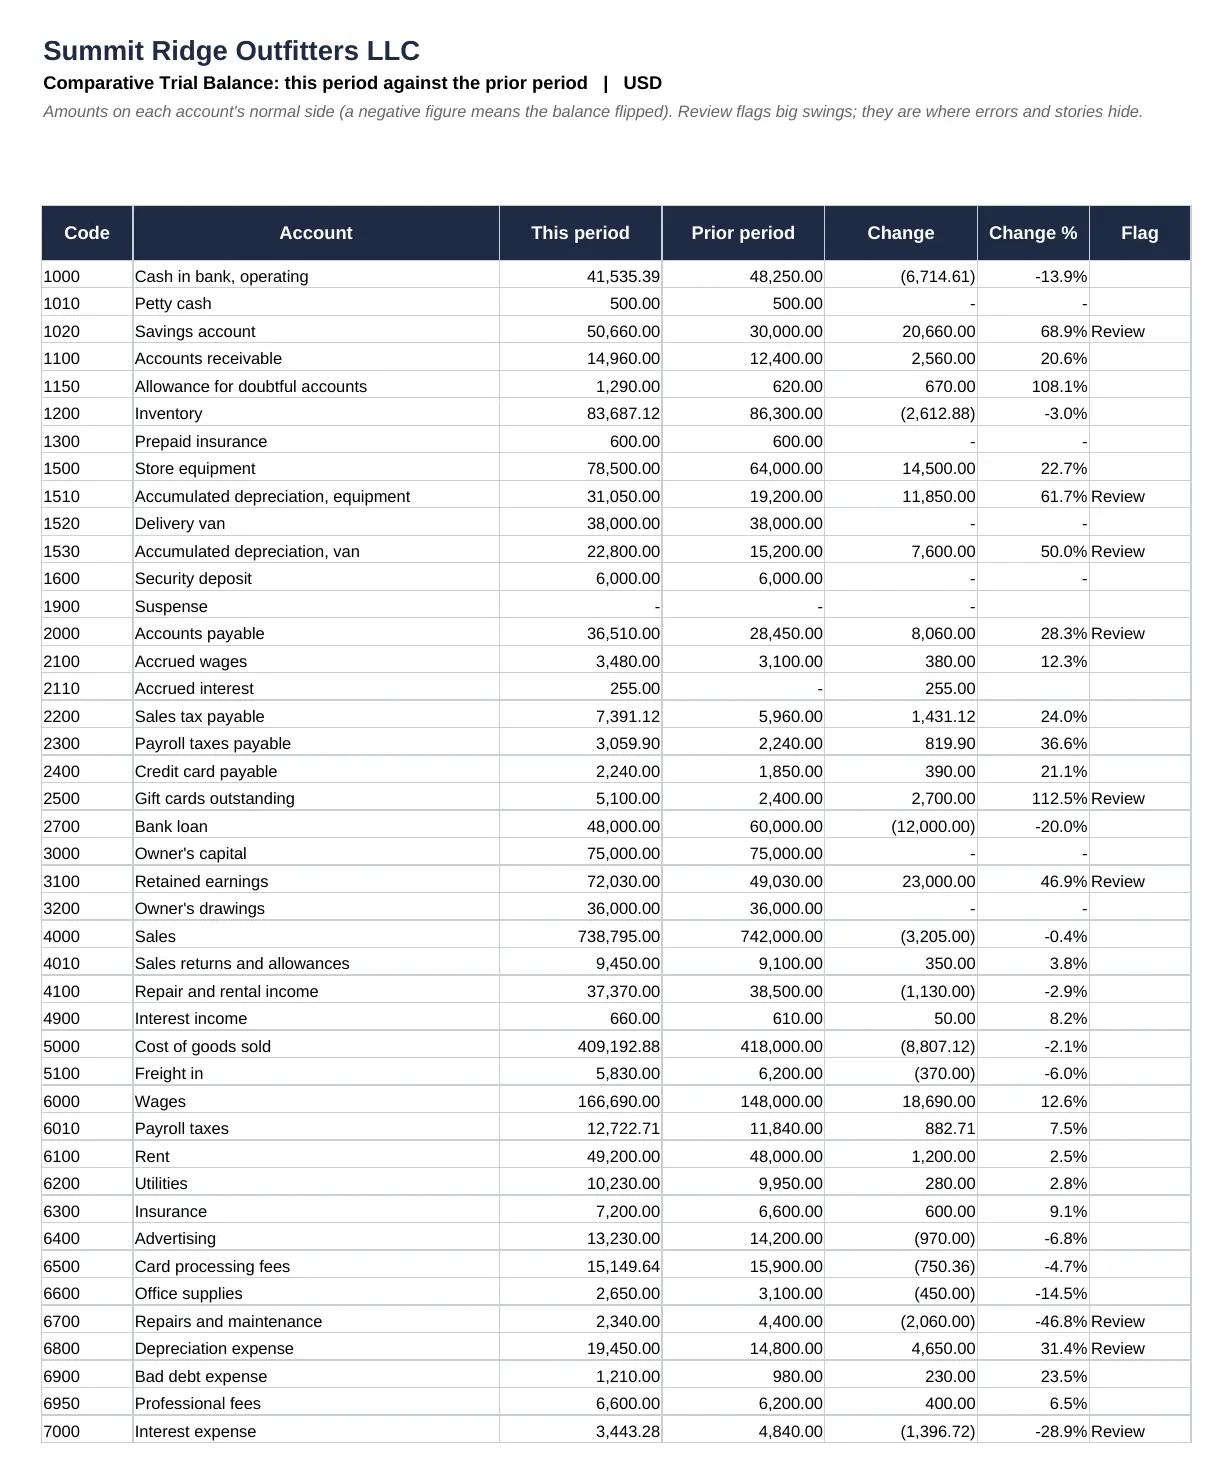
Two layouts and a Word pack for paper. Keep the standard trial balance format in Excel, or switch to the Indian layout (Particulars, L.F., debit and credit) in one click. The Word file adds a blank simple format, the Indian format, a filled adjusted trial balance example, a blank 10-column worksheet and a cheat sheet with the checks to run when it does not balance.
Trial Balance Example (Filled Sample)
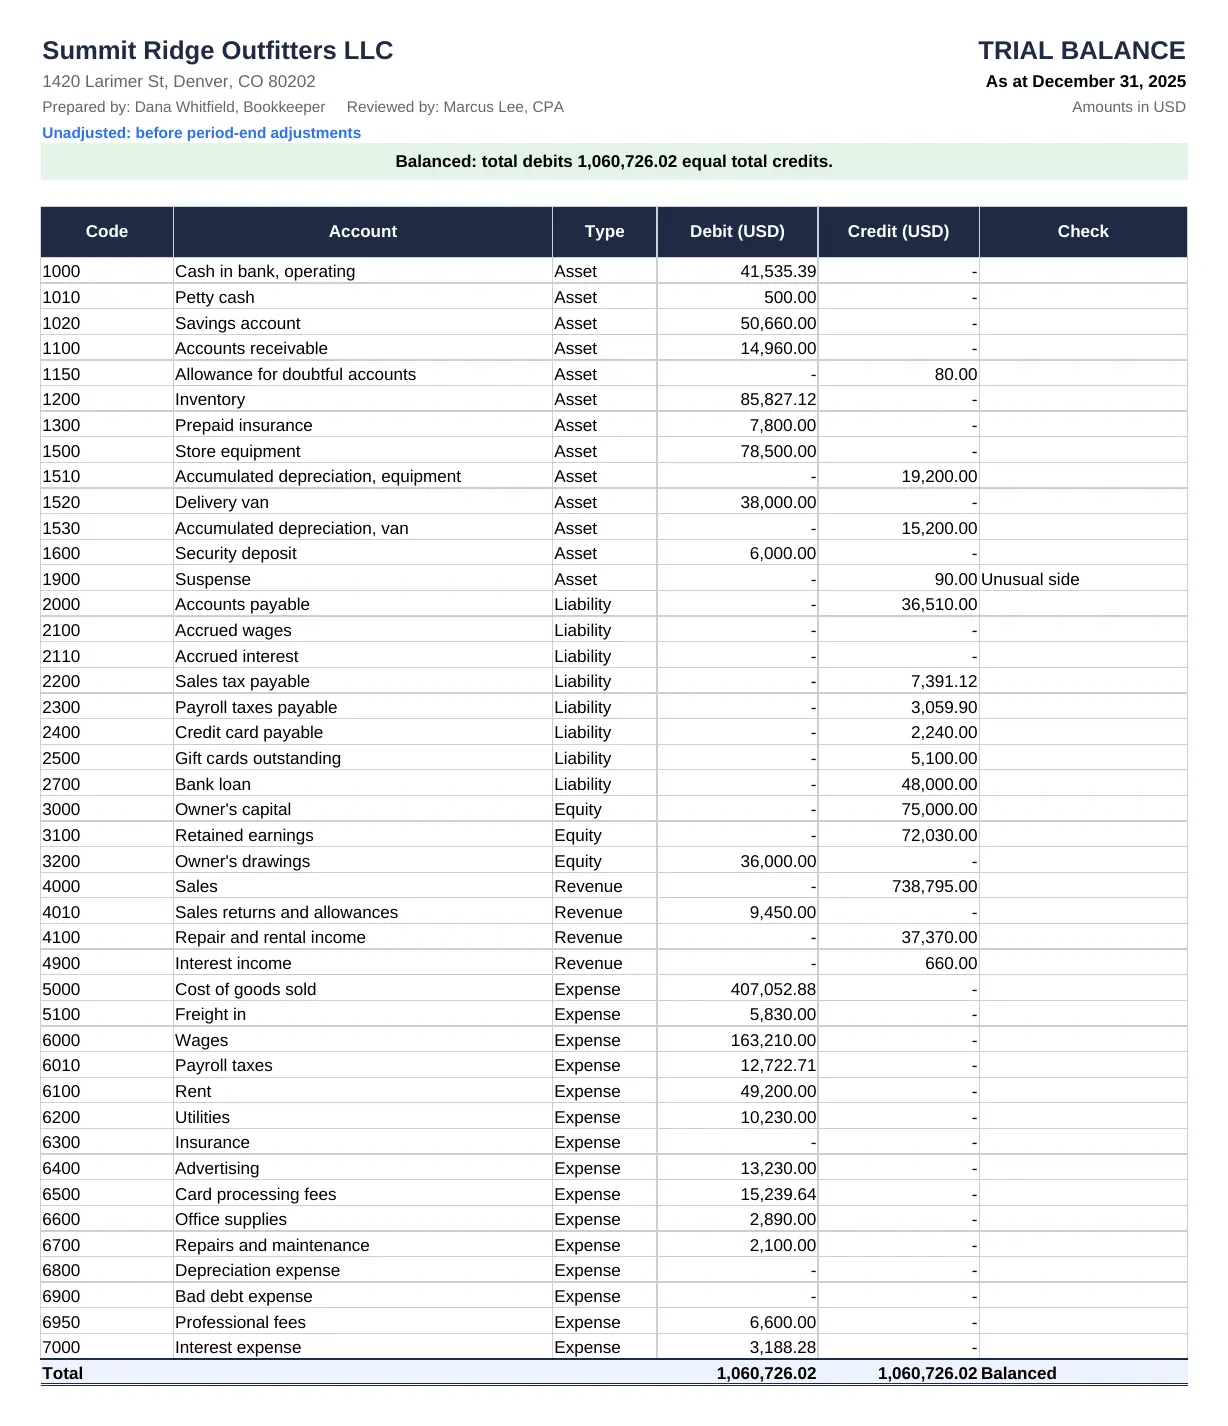
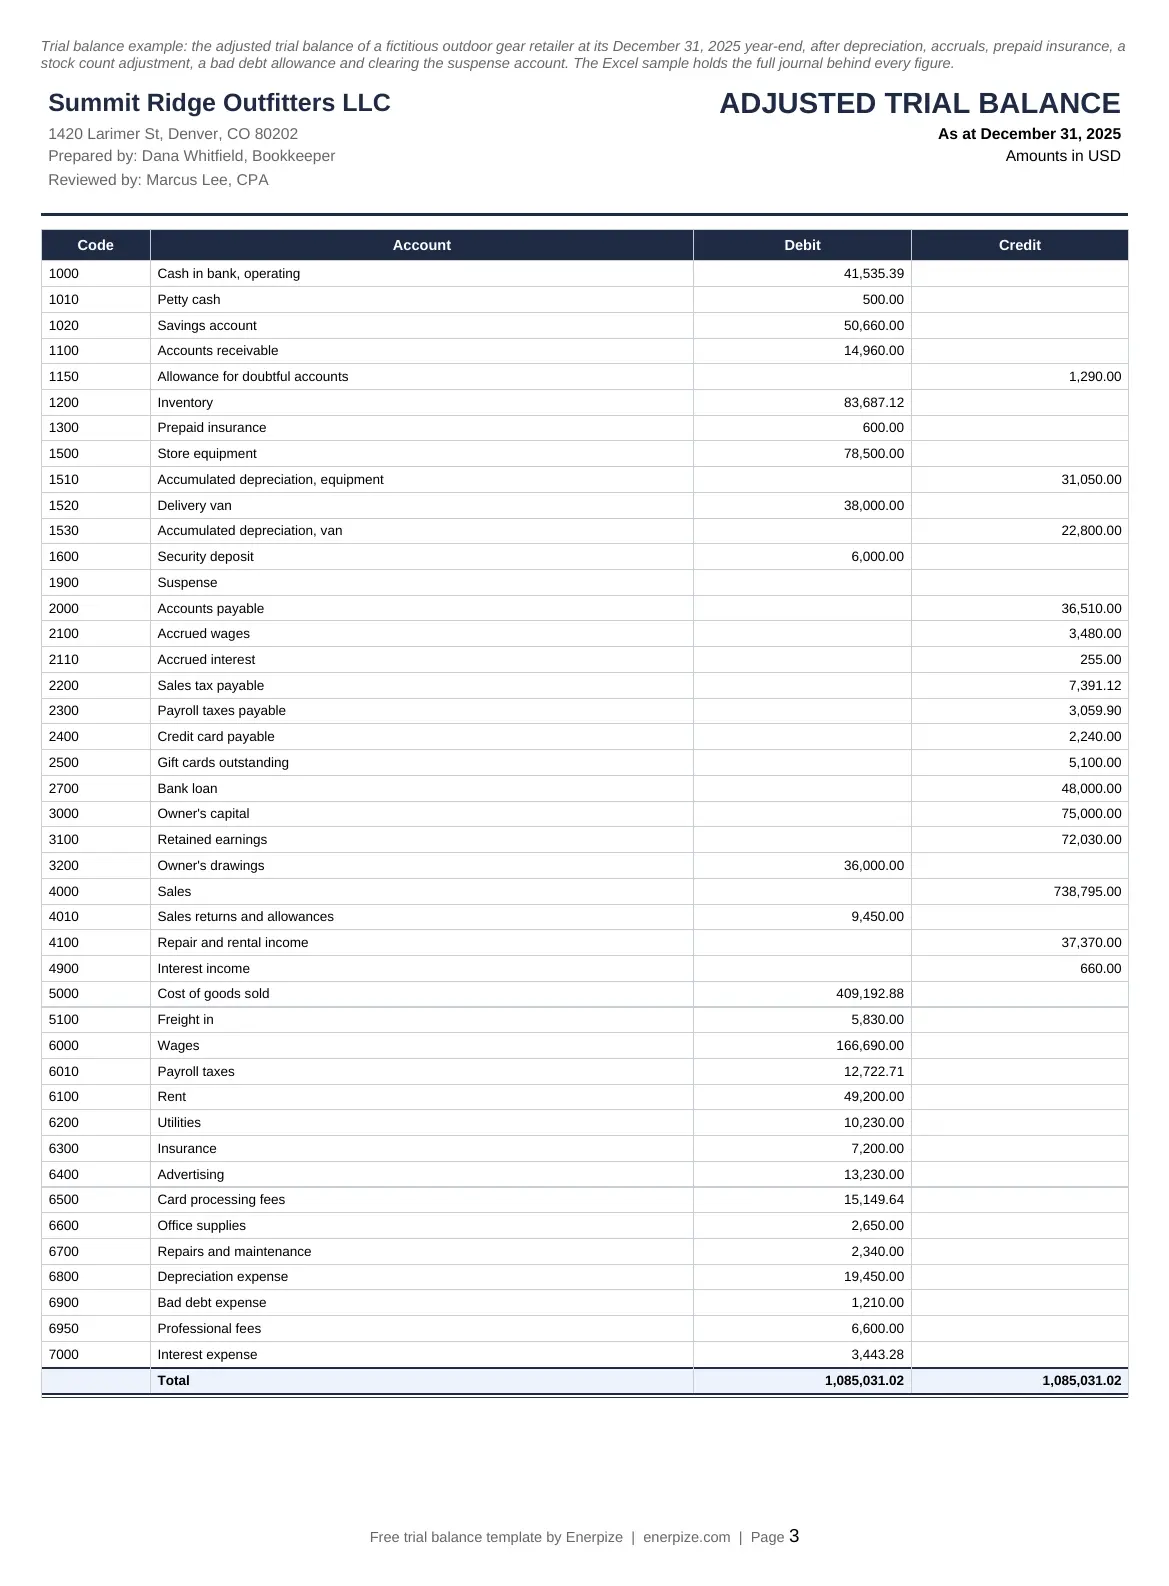
The fastest way to learn a trial balance is to read one that has already been prepared. So I built a full sample: Summit Ridge Outfitters LLC, a fictitious outdoor gear retailer in Denver, closing its books on December 31, 2025, in US dollars.
Make a copy of the filled trial balance sample in Google Sheets. Here is what is inside:
- A chart of accounts with 43 accounts, each with its type, normal side and statement line
- Opening balances at January 1, 2025, and last year's balances for the comparative trial balance
- 585 journal lines covering a year of sales, purchases, payroll, rent, sales tax, loan payments and owner's draws
- 9 year-end adjusting entries: depreciation, prepaid insurance, accrued wages, accrued interest, a stock count adjustment, a bad debt allowance, a reclassification and clearing a suspense balance
- The unadjusted, adjusted and post-closing trial balances, the extended trial balance, the financial statements and a ledger view, all calculated
The unadjusted trial balance totals 1,060,726.02 on both sides. The adjustments add 34,065.00 to each side, and the adjusted trial balance totals 1,085,031.02. The year closes with a net profit of 42,236.49 and total assets of 259,302.51. Delete the sample rows, type your own chart of accounts, and the same file becomes yours.
How to Read the Sample
Watch what the adjustments do to five accounts. This is the difference between an unadjusted and an adjusted trial balance, in real numbers.
| Account | Unadjusted | Adjustment | Adjusted | Why |
|---|---|---|---|---|
| Inventory | 85,827.12 Dr | 2,140.00 Cr | 83,687.12 Dr | The stock count came in lower than the books. |
| Prepaid insurance | 7,800.00 Dr | 7,200.00 Cr | 600.00 Dr | January from last year's policy and eleven months of the new one were used. |
| Accumulated depreciation, equipment | 19,200.00 Cr | 11,850.00 Cr | 31,050.00 Cr | A year of depreciation on store equipment. |
| Wages | 163,210.00 Dr | 3,480.00 Dr | 166,690.00 Dr | The last week of December was earned but not yet paid. |
| Suspense | 90.00 Cr | 90.00 Dr | Nil | A November difference turned out to be a card fee refund. |
Notice the suspense line. In the unadjusted trial balance, a 90.00 credit sits on an asset account, so the template flags it as being on its unusual side. That is exactly how a real close works: you park a difference you cannot explain yet, then clear it with an adjusting entry once you find it.
Trial Balance Format in Excel (With Formulas)
The standard trial balance format in Excel has a three-line header (business name, "Trial Balance", and the "as at" date) and four columns: account code, account name, debit and credit. Accounts follow the chart of accounts order: assets, liabilities, equity, revenue, then expenses. That order matters, because the first three groups become the balance sheet and the last two become the income statement.
Here is a simple trial balance format with numbers, for a small consulting business at the end of a month.
| Code | Account | Debit | Credit |
|---|---|---|---|
| 1000 | Cash | 18,400 | |
| 1100 | Accounts receivable | 6,200 | |
| 1500 | Equipment | 12,000 | |
| 1510 | Accumulated depreciation | 2,400 | |
| 2000 | Accounts payable | 3,100 | |
| 2500 | Unearned revenue | 1,200 | |
| 3000 | Owner's capital | 20,000 | |
| 3200 | Owner's drawings | 1,500 | |
| 4000 | Service revenue | 19,300 | |
| 6100 | Rent | 2,500 | |
| 6000 | Wages | 4,800 | |
| 6200 | Utilities | 600 | |
| Total | 46,000 | 46,000 |
To make that trial balance format in Excel calculate for you, these are the formulas that matter. Our template uses all of them.
- Totals:
=SUM(D8:D50)for debits and=SUM(E8:E50)for credits. - Balance check:
=IF(ABS(SUM(D8:D50)-SUM(E8:E50))<0.01,"Balanced","Out of balance"). Use a small tolerance, not an exact match, because cents can round. - Pull a balance from the journal:
=SUMIFS(Journal!F:F,Journal!C:C,A8)-SUMIFS(Journal!G:G,Journal!C:C,A8)gives the account's net movement, debits minus credits. - Split a net balance into the right column: debit
=MAX(net,0), credit=MAX(-net,0). This is also how you turn a single-column export from any software into a two-column trial balance. - Transposition test:
=MOD(ROUND(ABS(difference)*100,0),9)=0returns TRUE when the difference divides evenly by 9.
Using the Indian format? The columns become Particulars, L.F. (ledger folio), Debit Balance and Credit Balance, and the header reads "Trial Balance as on 31st March". The template switches between both layouts from the Settings sheet.
Debit and Credit Balances: Which Side Does Each Account Go On?
Every account has a normal side, the side its balance usually sits on. Assets and expenses are debit accounts. Liabilities, equity and revenue are credit accounts. Contra accounts sit on the opposite side of the group they belong to.
| Account group | Normal balance | Examples |
|---|---|---|
| Assets | Debit | Cash, receivables, inventory, prepaid expenses, equipment |
| Contra assets | Credit | Accumulated depreciation, allowance for doubtful accounts |
| Liabilities | Credit | Accounts payable, accrued expenses, taxes payable, loans |
| Equity | Credit | Owner's capital, share capital, retained earnings |
| Drawings or dividends | Debit | Owner's drawings, dividends declared |
| Revenue and income | Credit | Sales, service revenue, interest income |
| Contra revenue | Debit | Sales returns, sales discounts |
| Expenses | Debit | Cost of goods sold, wages, rent, depreciation, interest |
A balance on the opposite side is not always an error. A bank overdraft puts cash in credit, and an overpaid supplier puts accounts payable in debit. But each one deserves a second look, which is why the template flags them.
Types of Trial Balance
All three main types use the same format. What changes is when you prepare them and what they include.
Unadjusted Trial Balance
Prepared straight from the ledger after the period's transactions are posted, before any adjustments. It is your first test: do the day-to-day entries balance? In the sample, it totals 1,060,726.02 on both sides.
Adjusted Trial Balance
Prepared after adjusting entries for depreciation, accruals, prepayments, inventory counts, bad debts and corrections. This is the version you prepare financial statements from, because it puts income and expenses in the right period. In the sample, the adjustments add 34,065.00 to each side.
Extended Trial Balance
The extended trial balance, also called the 10-column worksheet, puts the unadjusted trial balance, the adjustments and the adjusted trial balance side by side, then splits every account into income statement and balance sheet columns. It is the classic bridge from the trial balance to the final accounts, and still the way many accountants and students prepare year-end figures by hand.
Post-Closing Trial Balance
Prepared after closing entries move revenue, expenses and drawings into retained earnings. Only balance sheet accounts remain, and they become next period's opening balances. In the sample, the post-closing trial balance totals 314,442.51.
Totals Method vs Balances Method
There are two ways to fill a trial balance. The totals method lists each account's total debits and total credits for the period, so an account can show figures in both columns. The balances method nets them and shows only the closing balance, in one column. Both should balance. The balances method is the standard for financial statements, and it is what our template produces; the ledger view shows the totals behind each balance.
How to Use the Trial Balance Template
1- Set Up the Period
On the Settings sheet, enter the business name, the period start and end dates, the currency and who prepares and reviews it. Pick the layout (the standard trial balance format in Excel with code and account, or the Indian Particulars and L.F.) and whether to show every account or only accounts with balances.
2- Build the Chart of Accounts
Enter each account's code, name, type and statement line, in chart of accounts order. Mark contra accounts such as accumulated depreciation, allowance for doubtful accounts, sales returns and drawings as contra, so the template knows their normal side. The blank file starts with 56 common accounts you can edit. Our chart of accounts template has more ideas for structuring codes.
3- Enter Opening Balances
Enter each balance sheet account's balance at the start of the period, on its debit or credit side. Revenue and expense accounts start at zero in a new financial year. Check the opening totals agree before you go further; the Error Finder tells you if they do not.
4- Post Journal Entries, or Paste Balances
Record each transaction in the journal with a reference shared by all its lines. The Check column turns red the moment an entry's debits and credits disagree. If your books live in other software, paste its trial balance into Import TB instead. For the journal itself, our journal entry template covers the common entries.
5- Check the Trial Balance
Open the trial balance. The banner at the top says balanced or out of balance, and the Check column flags any account on its unusual side. If it is out, open the Error Finder and work down the list from the top.
6- Post Adjusting Entries
Record depreciation, accruals, prepayments, the stock count, bad debts and any corrections on the Adjustments sheet. Clear any suspense balance here too. Each adjusting entry must balance on its own.
7- Read the Adjusted Trial Balance and Statements
Check that the adjusted trial balance balances, then review the extended trial balance, the income statement and the balance sheet. Use the comparative trial balance to question every account the template flags for a big swing.
8- Close the Period and Keep the Records
Save the adjusted and post-closing trial balances as PDFs with the date in the file name, and carry the post-closing balances forward as next period's opening balances. Keep the trial balance with the ledger and source documents for as long as your country requires, which is 3 to 8 years in the four countries covered below.
Why Your Trial Balance Does Not Balance (and How to Find the Error)
An out-of-balance trial balance always means the same thing: somewhere, a debit and a credit were not recorded as equal amounts. Work through these checks in order. They find most differences in minutes.
- Re-add both columns. Then check every ledger balance was copied across, and into the right column.
- Check the opening balances. A wrong brought-forward figure carries into every period after it.
- Divide the difference by 9. If it divides evenly, look for transposed digits (540 entered as 450) or a slide (1,000.00 entered as 100.00). In the Error Finder example, 5,400 divided by 9 is exactly 600.
- Halve the difference. An amount posted to the wrong side doubles into the difference, so look for a line equal to half of it.
- Look for the whole difference. A line equal to the full difference may be missing its other half.
- Check each entry balances. Then review accounts sitting on their unusual side.
- Still stuck? Park the difference in a suspense account so you can carry on, and clear it with a correcting entry the moment you find the cause.
Errors a Trial Balance Will Not Catch
A balanced trial balance proves debits equal credits. It does not prove the books are right. These errors all balance perfectly:
- Omission: a transaction never recorded at all.
- Commission: the right amount in the wrong account of the same type, such as paying supplier A and posting it to supplier B.
- Principle: the right amount in the wrong type of account, such as booking new equipment as a repairs expense.
- Original entry: the wrong amount on both sides of an entry.
- Reversal: the debit and credit swapped between the two accounts.
- Compensating errors: two mistakes that cancel each other out.
- Duplication: the same entry posted twice.
That is why a trial balance is a starting point, not a sign-off. Reconcile the bank, receivables and payables as well, and use the comparative trial balance to question any account that moved more than you expected.
Trial Balance vs Balance Sheet vs General Ledger
| General ledger | Trial balance | Balance sheet | |
|---|---|---|---|
| What it holds | Every transaction, account by account | One closing balance per account | Assets, liabilities and equity only |
| Includes revenue and expenses? | Yes | Yes (except post-closing) | No, they become net profit in equity |
| Purpose | Record and trace | Prove debits equal credits | Report financial position |
| Audience | Accounting team | Accounting team and auditors | Owners, lenders, investors, tax authorities |
| Format rules | Your system's | Two columns, debit and credit | Accounting standards such as GAAP or IFRS |
The rule to remember: the ledger feeds the trial balance sheet, and the adjusted trial balance feeds the financial statements. Read more in Enerpize's full guide to the trial balance.
From Trial Balance to Financial Statements
Once the adjusted trial balance balances, the statements are a mapping exercise. Give every account a statement line, then total the lines.
- Income statement: revenue minus cost of goods sold is gross profit; minus operating expenses and depreciation is operating profit; plus other income, minus interest and tax is net profit. In the sample: revenue 766,715.00, gross profit 351,692.12 (a 45.9% margin), net profit 42,236.49.
- Balance sheet: assets on one side, liabilities and equity on the other. Equity is opening capital and retained earnings, plus net profit, minus drawings. In the sample, total assets are 259,302.51, liabilities 106,036.02 and equity 153,266.49.
- The check: total assets must equal liabilities plus equity. If they do not, an account is mapped to the wrong line or has no line at all.
In Excel, the mapping is one formula per line: =SUMIFS(adjusted balance column, statement line column, "Inventory"). Our template does it for every line, and shows the prior period next to it. For a deeper look at the first statement, read Enerpize's guide to the profit and loss statement.
Importance of the Trial Balance Template
Catches Errors Before They Spread
A one-sided entry found at month-end takes minutes to fix. The same error found after the tax return is filed takes an amended return, and sometimes a penalty. The trial balance is the cheapest place in the accounting cycle to find a mistake.
Makes Financial Statements Possible
The income statement and balance sheet are built from the adjusted trial balance. If the trial balance is wrong, both statements are wrong, and so is every ratio a lender calculates from them.
Speeds Up the Month-End Close
A consistent template means the same checks, in the same order, every month. The Error Finder turns hours of hunting into a list of suspects.
Gives Auditors and Accountants a Clean Starting Point
External accountants usually ask for the trial balance first. A dated, reviewed trial balance with its adjustments listed separately saves them time, and saves you their fees.
Shows How the Business Is Changing
A single trial balance is a snapshot. Two side by side show the story: receivables growing faster than sales, a cost line that doubled, a gift card liability that will need cash later. The comparative trial balance flags those for you.
Who Can Use the Trial Balance Template?
Small Business Owners
Owners who keep their own books get a trial balance sheet that works as a clear test that the numbers add up before they file taxes or talk to the bank.
Bookkeepers
A repeatable month-end routine: post, check, find the error, adjust, close.
Accountants and Accounting Firms
Paste a client's trial balance from any software, post your adjusting entries separately, and get the extended trial balance and draft statements in one file.
Accounting Students
The extended trial balance, adjusting entries, closing entries and error types are core exam topics for ACCA, CA and CPA students. The filled sample shows every step with real numbers.
Finance Teams in Growing Companies
Use the comparative trial balance to review month-on-month movements before management accounts go out.
How Enerpize Produces Your Trial Balance Automatically
A spreadsheet works while one person posts the entries. Once sales, purchases, payroll and expenses come from different people and branches, typing every transaction twice stops making sense. In Enerpize accounting software, the trial balance is a report, not a project.
Entries That Post Themselves
Every invoice, purchase, expense, payment and payroll run posts its journal entry to the general ledger automatically. The chart of accounts comes ready-made with main and sub accounts you can edit, and manual journal entries sit alongside the automatic ones. Depreciation runs on its own through asset management, using straight-line, declining balance or units of production.
A Trial Balance Report With Real Filters
Go to Reports, then Accounting Reports, then Trial Balance. Filter by date range, main or sub accounts, a specific account, account branch, journal branch, the user who added the entries, account level, cost centers and tags. Choose to show all accounts, only accounts with transactions, or hide zero balances, and show net balances or separate debit and credit totals. Print it, or export it to Excel, CSV or PDF.
Ledger, Nets and Chart of Accounts Reports
The Trial Balance and Nets report, the Trial Nets report, the Ledger report and the Chart of Accounts Directory report sit next to it, so you can move from a balance to the entries behind it in a couple of clicks. And if you only need to bill a client today, the free invoice maker creates the invoice whose entry will later land in that trial balance.
Trial Balance Rules by Country
No country asks you to file a trial balance. But every country asks you to keep the books it summarizes, and to keep them for years. Here is what matters in the four countries where this template is used most.
United States
The IRS generally asks you to keep the records that support a tax return for 3 years, and longer in some cases: 7 years if you claim a loss from worthless securities or a bad debt deduction. Most US small businesses prepare statements under US GAAP or the tax basis, and the trial balance is what their CPA starts from.
What to add for US businesses:
- Separate accounts for sales tax payable by state if you collect in more than one
- An owner's drawings or distributions account, kept apart from expenses
- The trial balance date matching your tax year end
Practical note for US businesses: keep a bad debt allowance account even if you write off debts directly for tax. Your trial balance should show what you expect to collect, not just what customers owe.
India
Companies keep books of account under Section 128 of the Companies Act, 2013, and must preserve them for not less than eight financial years. Financial statements follow the Schedule III format, so it pays to group trial balance accounts the same way from the start.
What to add for Indian businesses:
- The Particulars and L.F. layout, with the trial balance dated "as on 31st March"
- Separate ledgers for input and output GST (CGST, SGST and IGST)
- TDS receivable and payable accounts
Practical note for Indian businesses: map every account to its Schedule III line before year-end. Re-grouping 200 ledgers in April, while the auditor waits, is where closing timetables slip.
Philippines
Under the Ease of Paying Taxes rules, books of accounts and other accounting records are preserved for five years, counted from the day after the return's due date or the date it was filed, whichever is later. VAT-registered businesses track output and input VAT at 12%.
What to add for Philippine businesses:
- Output VAT and input VAT as separate accounts
- Expanded withholding tax payable and creditable withholding tax accounts
- A trial balance for each period you file, saved with the books
Practical note for Philippine businesses: reconcile the VAT accounts in the trial balance to your returns every quarter. Differences found at year-end are much harder to explain.
South Africa
The Companies Act, 2008 requires companies to keep accurate accounting records for seven years. For tax, SARS asks you to keep records for five years from the date a return is submitted. Many small companies report under IFRS for SMEs.
What to add for South African businesses:
- VAT input and output accounts at 15%
- PAYE, UIF and SDL payable accounts for payroll
- A provisional tax account, so payments do not land in expenses
Practical note for South African businesses: keep the seven-year Companies Act period as your rule. It is the longer of the two, so meeting it covers SARS as well.
Key Takeaways
- A trial balance lists every ledger account's closing balance in a debit or credit column; the two totals must be equal.
- Assets, expenses and drawings are normally debits. Liabilities, equity and revenue are normally credits. Contra accounts sit on the opposite side.
- Use the unadjusted trial balance to test your entries, the adjusted trial balance to prepare statements, and the post-closing trial balance to open the next period.
- If it does not balance, divide the difference by 9, halve it, and look for unbalanced entries and wrong opening balances.
- A balanced trial balance can still hide omissions, wrong accounts, reversals and compensating errors.
- Map each account to a statement line, and the adjusted trial balance becomes the income statement and balance sheet.
- The trial balance format in Excel needs four columns (code, account, debit, credit), SUM totals and a check that the difference is zero.
- Our free trial balance template does all of this by formula in Excel and Google Sheets, with Word and PDF formats for print.
FAQs
What is a trial balance?
A trial balance is a list of every general ledger account with its closing balance in a debit or a credit column at a set date. The two columns are totaled to prove that debits equal credits before financial statements are prepared.
What is the trial balance format in Excel?
A header with the business name, "Trial Balance" and the "as at" date, then four columns: account code, account name, debit and credit. Total both columns with SUM and add a check that the difference is zero. The Indian format uses Particulars, L.F., Debit and Credit.
How do you prepare a trial balance?
Post all journal entries to the ledger, work out each account's closing balance, and list it in the debit or credit column. Total both columns and compare them. If they differ, find and correct the error before you prepare financial statements.
What is an example of a trial balance?
A small business might list cash 18,400, receivables 6,200, equipment 12,000, drawings 1,500 and expenses 7,900 as debits, and accumulated depreciation, payables, unearned revenue, capital and revenue as credits. Both columns total 46,000, so it balances.
What are the rules of a trial balance?
Every ledger account with a balance is included. Each balance goes in one column only. Assets and expenses are normally debits; liabilities, equity and revenue are normally credits. Total debits must equal total credits.
What is the difference between a trial balance and a balance sheet?
A trial balance lists every account, including revenue and expenses, to check that debits equal credits, and stays internal. A balance sheet is a financial statement showing only assets, liabilities and equity, prepared from the adjusted trial balance for owners and lenders.
What should I do if my trial balance does not balance?
Re-add both columns, check the opening balances, then divide the difference by 9 (transposed digits) and halve it (an amount on the wrong side). Look for entries whose debits and credits differ. If you cannot find it yet, park the difference in a suspense account and clear it later.
What errors are not revealed by a trial balance?
Errors of omission, commission, principle and original entry, reversed entries, compensating errors and duplicated entries. All of them leave debits equal to credits, so the trial balance still balances.
What is the difference between an adjusted and an unadjusted trial balance?
The unadjusted trial balance comes straight from the ledger before period-end adjustments. The adjusted trial balance includes depreciation, accruals, prepayments, inventory and other adjusting entries, and is the one used to prepare financial statements.
What is an extended trial balance?
A 10-column worksheet that shows the trial balance, adjustments and adjusted trial balance side by side, then splits each account into income statement and balance sheet columns. Net profit is the figure that balances the last two pairs.
How often should you prepare a trial balance?
At least monthly, as part of the month-end close, and always before preparing financial statements or a tax return. Businesses with heavy volume often run one weekly to catch errors sooner.
About the Author
Omar El Bahr is a Senior Digital Growth Specialist at Enerpize, where he leads SEO, content strategy, and organic growth across international markets. He is a Forbes Communications Council contributor and has written for Entrepreneur on business communication and digital strategy.
Disclaimer
This trial balance template and guide are for general business use and are not accounting, audit or tax advice. The sample business is fictitious. Record-keeping and reporting rules change and vary by country, so confirm them with the relevant authority or a qualified accountant.